
HMO Fire Risk Assessment London
Avoid £30k fines and property closure. Get your legally compliant HMO fire risk assessment with guaranteed 24-hour turnaround from BAFE SP205 accredited engineers.

Trusted & Accredited


Why Every HMO Landlord in London Must Have This
Enforcement actions against HMO landlords increased 12% last year. Don't risk your rental income with non-compliance.
It's the law. Under the Regulatory Reform (Fire Safety) Order 2005 and Housing Act 2004, every HMO landlord must have a current fire risk assessment—no exceptions. Here's the reality: only 60% of HMO audits pass inspection (lowest since 2011). The other 42% face enforcement notices, fines up to £30k, and potential property closure. Where does your property stand?
What Are Fire Risk Assessments for HMOs?
A fire risk assessment is a systematic examination of a building to determine fire causes and who could be harmed. It also assesses if the precautions in place are good enough. In an HMO, that means looking well beyond the obvious. Sleeping occupants, shared kitchens, several households who barely know one another, and a steady turnover of tenants are all risk factors.
Competent HMO Fire Risk Assessors walk the whole property, checking communal areas, escape routes, alarm coverage, doors, and everyday housekeeping. They also speak to whoever manages the building and look through the maintenance records. The visit is a Fire Hazard Assessment that weighs up ignition sources, combustible materials, and the people most at risk.
Everything is then put together in a written report, a Fire Safety Documentation. The report details the findings, ranks the actions by priority, and gives you a clear plan to work through. It also becomes your evidence, which matters if a fire officer, local authority, or insurer ever asks to see it.
Importance of HMO Fire Risk Assessment
It’s easy to treat the assessment as paperwork for its own sake. In reality, it has many benefits. Risk Assessment LTD helps HMO property owners understand and manage fire safety risks through a comprehensive fire risk assessment for HMO, with practical recommendations suited to their premises.
What Counts as an HMO Unit and Why Fire Risk Is Higher
Under the Housing Act 2004, an HMO is a property with at least three tenants from more than one household who share a kitchen, bathroom, or toilet. Fire safety is one of the biggest responsibilities that comes with it. A Fire Risk Assessment for HMO premises is where that responsibility starts. Why is the fire risk higher in HMO units than in a family home?
- More ignition sources. Phone chargers, hair straighteners, portable heaters, and e-bike batteries.
- Locked bedroom doors. A fire can develop unnoticed behind a door nobody else can open.
- No shared ownership of risk. Nobody "owns" the hallway, so nobody clears it.
- Older, converted buildings. Many HMOs are period houses with hidden voids, lath-and-plaster ceilings, and service pipes punched through walls.
That's why a fire risk assessment for HMO premises needs to go further than a glance at the smoke alarms. A proper Fire Hazard Assessment looks at how tenants live in the building, not how the floor plan suggests they should.
The Legal Requirements for an HMO Fire Risk Assessment
The core law is the Regulatory Reform (Fire Safety) Order 2005, usually called the FSO. It applies to the common parts of an HMO, such as hallways, stairs and landings. The regulation requires the responsible person to carry out a suitable and sufficient assessment and act on its findings. That Order has been tightened several times.
- Fire Safety Act 2021 confirmed the FSO covers the building's structure, external walls and flat entrance doors in multi-occupied residential buildings.
- Fire Safety (England) Regulations 2022, in force since 23 January 2023, require responsible persons in HMOs to give residents adequate fire safety information.
- Building Safety Act 2022 amendments, in force since 1 October 2023. Every assessment must have a detailed report, including the name of the assessor.
In short, the HMO Fire Risk Assessment Requirements are written, recorded and enforceable. Under the FSO, breaches can lead to unlimited fines and up to two years in prison. Respective councils can issue civil penalties of up to £30,000 under the Housing Act.
The responsible person for Fire Safety Management for HMOs is whoever has control of the premises. In most cases, that’s the landlord or owner. It can also be a managing agent or management company if they hold day-to-day control.
Landlords' and Tenants' Fire Safety Responsibilities
Where the landlord is the responsible person, the Regulatory Reform (Fire Safety) Order 2005 requires them to prioritise tenants’ safety. For instance, the landlord should conduct and review a fire safety assessment or hire a competent person to do it. They should also provide rules to enhance tenants’ safety, including banning indoor smoking.
Tenants, on the other hand, are expected to abide by the provided fire safety rules. However, they are not assigned the ‘responsible person’ tag by the FSO. Legal responsibility is with the landlord or the person in charge. Therefore, landlords should prioritise these assessments.
How We Protect Your Property & Income
Our proven 5-step process has helped 500+ London landlords pass inspections and avoid enforcement action.
Site Inspection
Comprehensive walk-through of all communal areas, escape routes, and fire safety equipment
Hazard Identification
Detailed evaluation of fire hazards specific to HMO configurations and occupancy patterns
Risk Evaluation
Assessment of people at risk including vulnerable occupants and escape route adequacy
System Testing
Verification of fire detection, alarm systems, emergency lighting, and fire door compliance
Report Delivery
Insurance-approved report with priority action plan delivered within 24 hours
8 Common Fire Safety Issues in HMOs
Having looked at a great many shared properties, we see the same problems come up again and again. At Risk Assessment LTD, our HMO fire risk assessment services are designed to provide landlords with clear guidance on managing fire safety across shared residential properties.
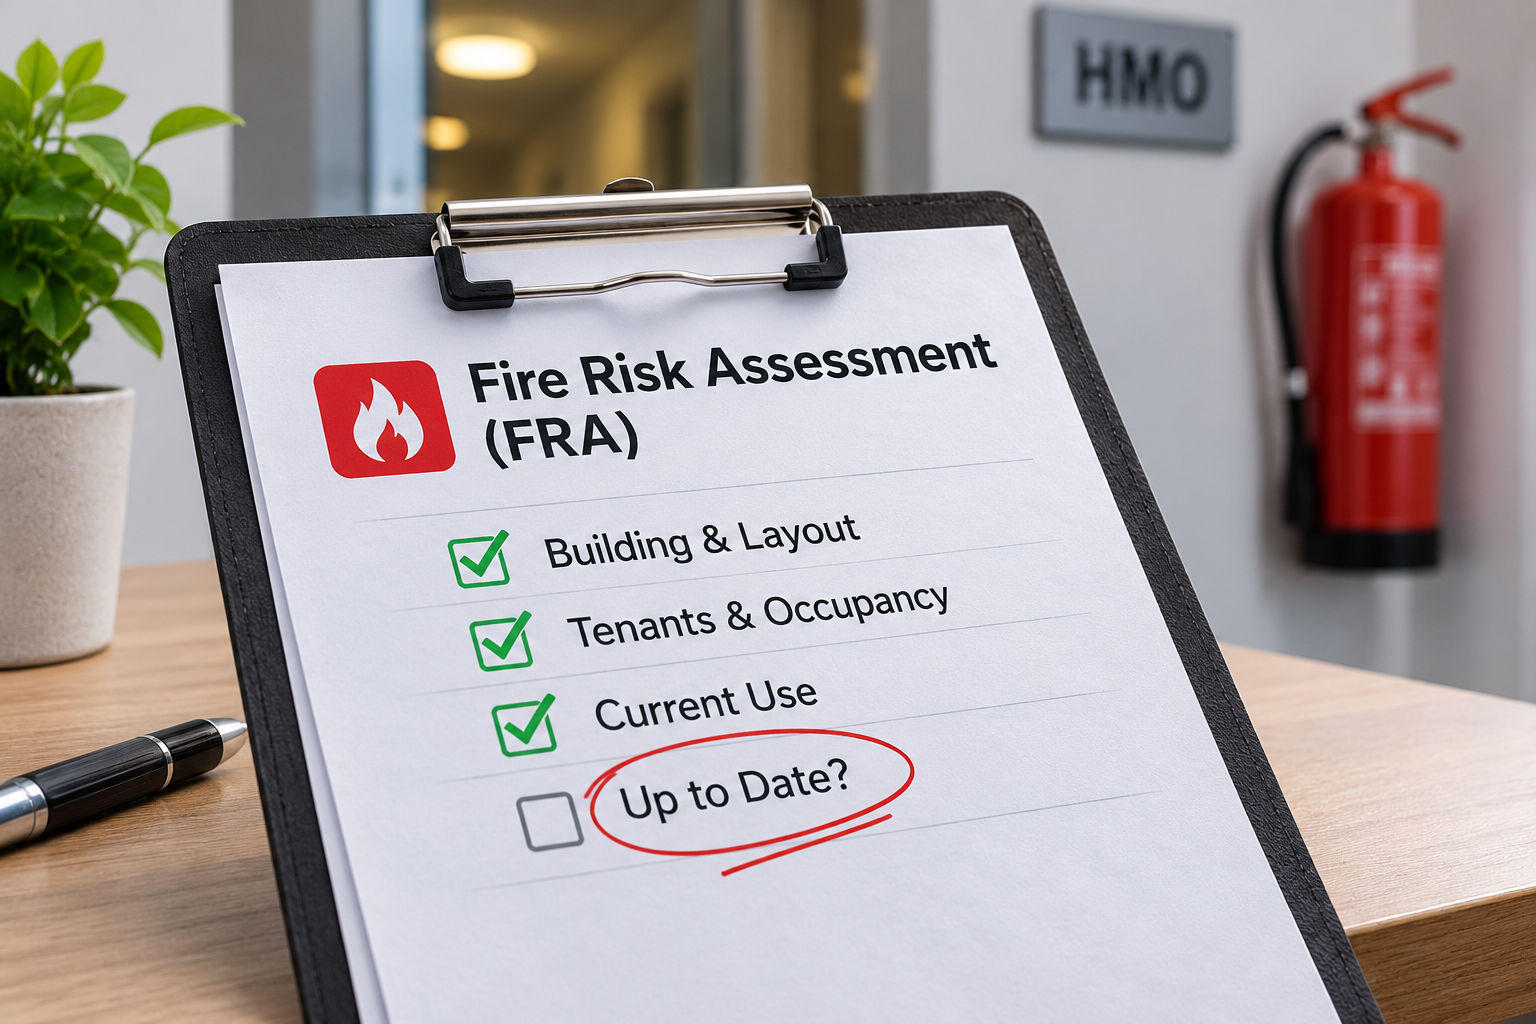
Outdated/Incomplete Fire Risk Assessments (FRAs)
An assessment written when the property was first licensed, or one that ignores recent changes, no longer reflects reality. A generic template is just as risky. A proper Fire Risk Assessment for HMO Property has to be specific to the building, its layout, its tenants, and its current use.

Shared Kitchen Fires
Cooking is the leading cause of accidental fires in the home, and in a shared kitchen the risks multiply. Unattended pans, greasy extractors, overloaded sockets, and careless tenants can increase fire risk. Appropriate Fire Extinguishers for HMOs, alongside a fire blanket in the kitchen, can help contain a small fire.

Electrical System Overload
Older properties and extension-lead culture simply don’t mix. Tenants each running laptops, kettles, tired wiring, and overloaded sockets become a genuine ignition risk. Fire risk assessment and regular portable appliance checks can reduce the chances of fire incidents.

Fire Door Tampering & Wedging
Reliable Fire Doors for HMO Properties need the right intumescent strips, smoke seals, and a closer that pulls to fully shut. Tenants prop them open for convenience, remove self-closers, or fit their own locks, making the door ineffective in holding back flame and smoke. A routine Fire Door Inspection catches gaps, damaged seals and loose hinges before they become a problem.
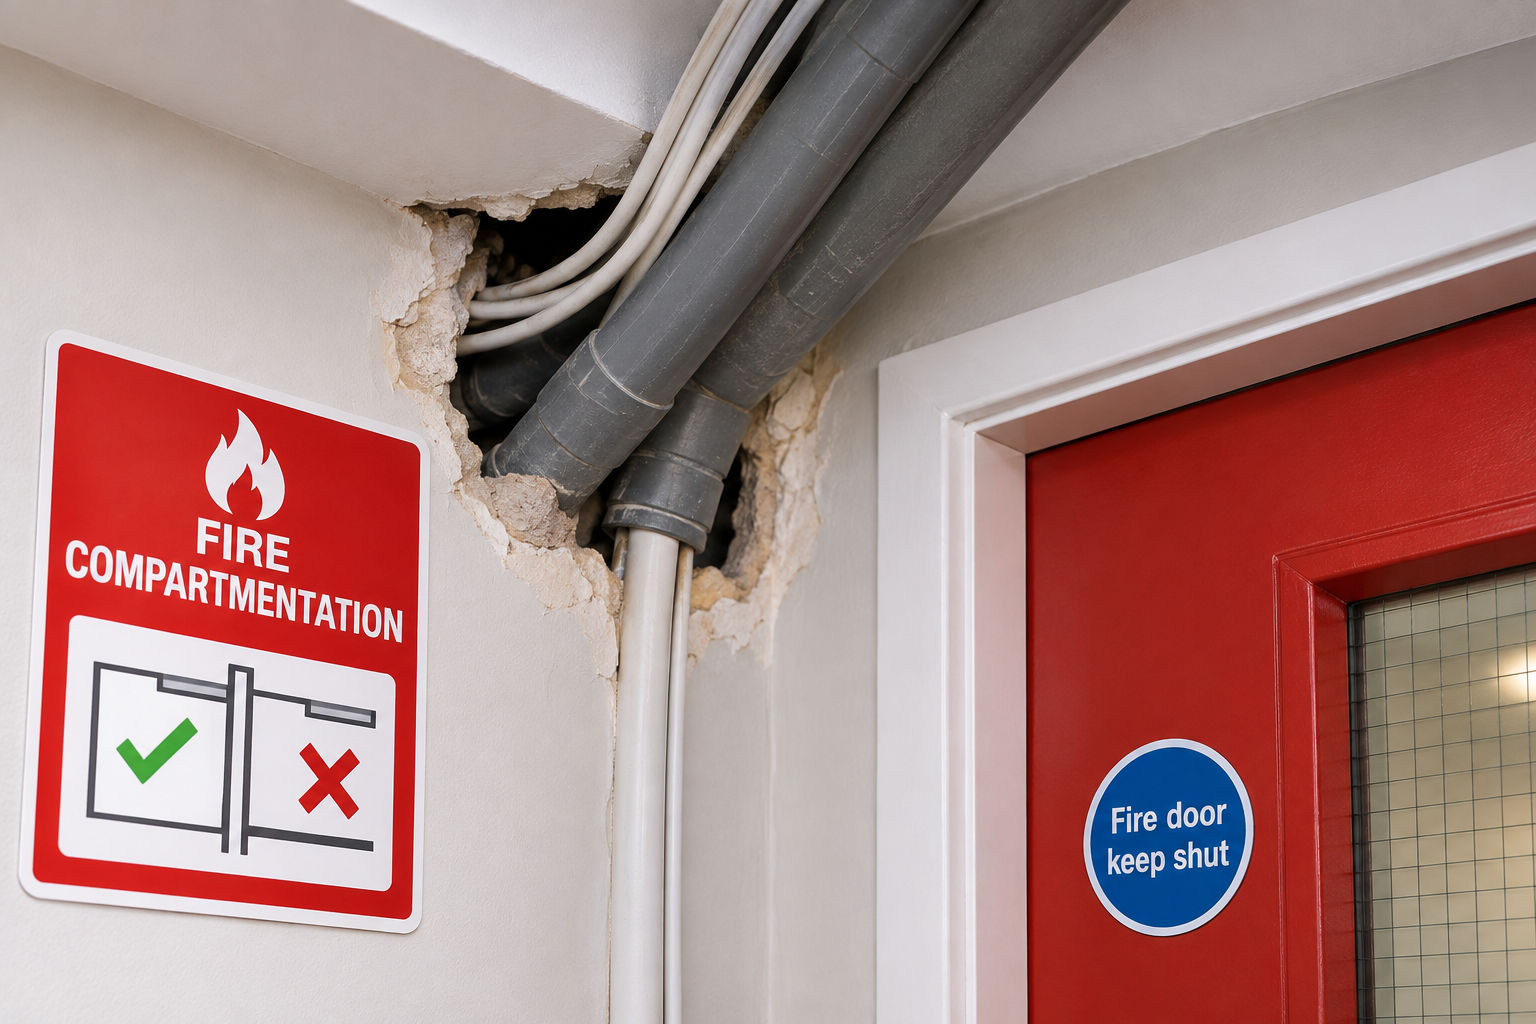
Inadequate Compartmentation
In many HMOs, fire compartmentation is compromised by gaps around pipes and cables, holes cut for new wiring, and damaged ceilings. Building Fire Strategy Reports can show how the building is meant to perform in a fire and the needed improvements.

Blocked Escape Routes
Bikes in the hallway, bags of rubbish under the stairs, and stored furniture all seem harmless, yet they can hamper Emergency Evacuation Plans. Your Fire Escape Routes need to stay free of obstruction at all times.

Tenant Fire Safety Awareness Gaps
Many tenants have never been told what to do when the alarm sounds. Strong Fire Safety Management for HMOs emphasises induction briefings, regular reminders, and clear house rules on cooking and candles. Tenants can quickly report faults such as a damaged door or a beeping alarm.

Inadequate Fire Detection Systems
A single smoke alarm in the hallway is not enough in an HMO. Most shared properties need an interlinked system, with detection covering escape routes and higher-risk rooms. A properly designed set of Fire Detection and Alarm Systems means everyone hears the alarm at the same time.
What You Get: Everything Inspectors Check
Your complete compliance package—every element fire officers examine during enforcement visits.
Fire Hazard Identification
Comprehensive evaluation of ignition sources, combustible materials, and HMO-specific fire risks including shared kitchens and electrical systems.
People at Risk Assessment
Evaluation of vulnerable occupants, occupancy levels, sleeping arrangements, and tenant awareness requiring tailored fire safety measures.
Fire Detection System Review
Compliance verification with BS 5839-6:2019 standards, Grade A/D system requirements, LD1/LD2/LD3 coverage levels, and interlinked alarm functionality.
Fire Door Inspection
FD30/FD60 fire door rating verification, self-closing mechanism testing, intumescent seal integrity, and compliance with Fire Safety (England) Regulations 2022.
Escape Route Evaluation
Travel distance measurements, corridor width verification, stairwell capacity analysis, final exit accessibility, and escape route lighting adequacy.
Management & Documentation
Fire safety management system review, tenant briefing procedures, fire action notices, maintenance records, and landlord compliance documentation.
Risk Rating Matrix
Standardized risk scoring system categorizing identified hazards by severity and likelihood, enabling prioritized remediation planning.
Priority Action Plan
Detailed remediation roadmap with specific recommendations, implementation timelines, regulatory references, and compliance verification methods.
Insurance-Approved Report
Professional documentation suitable for HMO licensing applications, mortgage lenders, insurance providers, and local authority compliance verification.
When an HMO Needs a Fire Risk Assessment
The short answer is before anyone moves in, and then whenever something changes. These are the key trigger points.
Why 500+ Landlords Trust Firerisk.io
Fast, affordable, and actually passes inspection. Here's what makes us different.
Inspectors Accept Our Reports (Every Time)
BAFE SP205 accredited means fire officers and local authorities accept our assessments without question. No rejected reports. No wasted money on reassessments. Just compliance.
Report in Your Inbox Tomorrow
Got an enforcement notice deadline? Licensing application due? We deliver your complete, inspection-ready report within 24 hours. Book today, compliant tomorrow.
We Know Every London Borough's Requirements
500+ HMOs assessed across all 32 boroughs means we know exactly what your local authority expects. Westminster? Done it. Tower Hamlets? Done it. Your borough? We've got you covered.
Know Your Price Before We Visit
No "call for quote" games. Use our instant calculator to see your exact price (£250-£850) based on your property. What you see is what you pay. No surprises. Ever.
Frequently Asked Questions (FAQs)
Don't Wait for an Enforcement Notice
Every day without a compliant fire risk assessment is a day you're risking fines, property closure, and invalidated insurance. Get protected in 24 hours.
Protect Your Property. Protect Your Income.
Join 500+ London landlords who sleep better knowing they're compliant. Book your assessment now.
Book Your Assessment Now